Managing multiple EMIs, credit card dues, and personal loans can make monthly finances difficult to organise. If you are considering a Debt Consolidation Loan in Delhi, one of the first questions that may come to mind is: How long will the loan take to get approved and disbursed?
The exact timeline can vary from one lender and borrower to another. It may depend on factors such as eligibility, documentation, credit profile, income, existing liabilities, verification, and the lender's internal process. Understanding these stages can help you prepare your application properly and avoid unnecessary delays.
What Is a Debt Consolidation Loan?
A debt consolidation loan is designed to help borrowers combine multiple outstanding debts into a single repayment arrangement. Instead of managing several lenders, interest rates, and payment dates, a borrower may use a new loan to repay eligible existing debts and then make repayments according to the new loan terms.
For example, someone managing credit card balances and multiple personal loans may explore debt consolidation in Delhi to simplify their repayment structure.
However, consolidation does not automatically reduce the total cost of borrowing. The interest rate, fees, tenure, and other terms should be carefully compared before making a decision.
How Long Does a Debt Consolidation Loan Take?
There is no single fixed processing time for every Debt Consolidation Loan in Delhi. The timeline can range from relatively quick processing to several business days, depending on how quickly the lender can verify the application and supporting information.
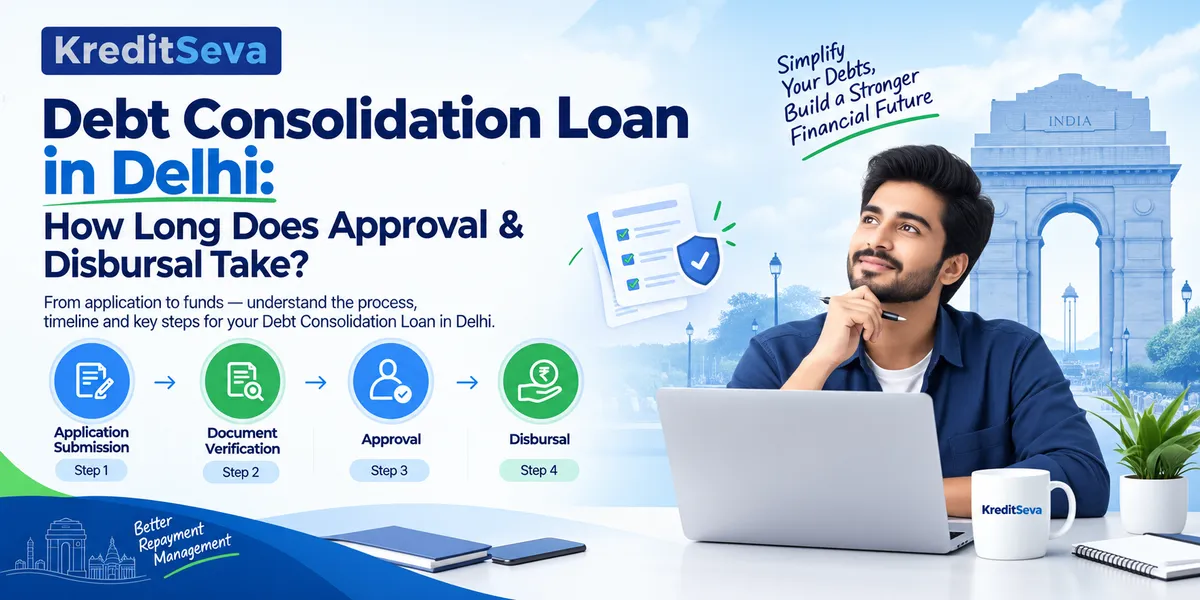
The process generally involves these stages:
1. Application Submission
The first step is completing the loan application and providing the requested information. This may include personal details, income information, employment or business details, existing loan obligations, and the amount you want to consolidate.
Providing accurate information from the beginning can help prevent avoidable delays.
2. Document Verification
After submitting the application, the lender may review documents such as identity proof, address proof, income documents, bank statements, and details of existing loans or credit-card balances.
Missing, unclear, or inconsistent documents may require additional clarification and can increase processing time.
3. Credit and Financial Assessment
The lender may assess your credit history, repayment behaviour, income, existing EMIs, and overall financial profile.
Your credit profile can be an important part of the assessment because lenders use financial information to determine whether you meet their lending criteria and what terms may apply.
4. Loan Approval
Once the lender completes its assessment, it may approve or decline the application based on its eligibility criteria.
For borrowers applying for a Debt Consolidation Loan in Delhi, approval time can depend on the complexity of the application and whether all required information has been successfully verified.
An approval decision should not be confused with guaranteed disbursal. The final stage may still involve agreement acceptance and completion of required formalities.
5. Loan Agreement and Disbursal
After approval, the borrower may need to review and accept the loan agreement and complete any remaining formalities. Once these steps are completed, the approved loan amount can be disbursed according to the lender's process and terms.
This is why the overall timeline from application to receiving funds can differ between borrowers.
What Can Delay Loan Approval?
Several factors may affect the processing time of a Debt Consolidation Loan in Delhi, including:
- Incomplete application details
- Missing documentation
- Difficulty verifying income or employment
- Multiple existing financial obligations
- Inconsistencies in submitted information
- Additional verification requirements
- Credit history that requires further assessment
- Delays in completing lender formalities
Preparing your documents in advance and providing accurate information can make the application process more organised.
Documents You May Need
The exact requirements vary by lender, but borrowers may commonly be asked for:
- Identity and address proof
- PAN or other applicable identification
- Salary slips or income proof
- Recent bank statements
- Employment or business information
- Existing loan statements
- Credit-card outstanding details
If you are planning to consolidate multiple debts, keeping your current loan and credit-card statements ready can make it easier to provide accurate information about your outstanding obligations.
How to Make the Process Smoother
Want to avoid unnecessary delays? Keep these points in mind before applying for a Debt Consolidation Loan in Delhi:
Check eligibility first: Understand the lender's basic requirements before submitting an application.
Keep documents ready: Having income, identity, bank, and existing debt documents available can reduce back-and-forth communication.
Review your existing debts: Calculate outstanding balances, current EMIs, interest rates, and remaining tenures before deciding how much you need.
Provide consistent information: Make sure the details in your application match your supporting documents.
Understand the loan terms: Don't focus only on how quickly the loan can be approved. Compare interest rate, processing fees, tenure, EMI, and other applicable charges.
Is Faster Approval Always Better?
Not necessarily. Speed can be convenient, but choosing a loan purely because it is processed quickly may cause you to overlook important terms.
When comparing a Debt Consolidation Loan in Delhi, consider the complete cost of borrowing and whether the proposed EMI fits your monthly budget. A slightly longer process may still be appropriate if it gives you enough time to understand the terms and complete the documentation correctly.
The goal of debt consolidation should be better repayment management—not simply getting another loan quickly.
Final Takeaway
The time required for a Debt Consolidation Loan in Delhi depends on several factors, including lender procedures, eligibility, documentation, credit assessment, verification, and completion of loan formalities. While some applications may move quickly, others can require additional checks.
Before applying, organise your documents, understand your outstanding debts, compare available loan terms, and check the lender's eligibility requirements. Taking these steps can make the overall debt consolidation loan process more straightforward and help you make a better-informed borrowing decision.
FAQs
1. How long does a Debt Consolidation Loan in Delhi take to get approved?
The approval timeline varies by lender and borrower. It can depend on documentation, eligibility, credit assessment, income verification, and the lender's internal processing procedures.
2. Can missing documents delay a debt consolidation loan?
Yes. Incomplete or unclear documentation may require additional information or verification, which can extend the processing timeline. Keeping the required documents ready can help make the process smoother.
3. Does quick loan approval mean the loan is better?
Not necessarily. Approval speed is only one factor. Before selecting a Debt Consolidation Loan in Delhi, compare the interest rate, fees, tenure, EMI, repayment conditions, and overall borrowing cost.